A home inventory for insurance
A claim is decided on evidence. Photographs, receipts, serial numbers and dated values — gathered before anything happens — are what turn a list of losses into a settled claim.
Contents insurance pays for what you can substantiate. After a fire, flood or burglary, an insurer will ask what was lost, what it was worth and what proves you owned it — usually while you are least able to reconstruct any of it from memory.
This page covers what to record, how to think about value, and how to keep the evidence somewhere it will survive the event you're insuring against — building on the room-by-room record described in the home inventory app page. It's general guidance, not advice about your policy.
Be ready before the claim form arrives
Record your contents in Vekrin and keep the photographs, receipts and values in one place your insurer can work from.
The evidence insurers tend to ask for
Requirements differ by insurer and by claim size, but the same handful of things come up again and again.
- A description — Make, model, size, material, colour — enough to identify a specific object.
- Photographs — The item in place, plus a close-up of any serial or model number.
- Proof of purchase — Receipt, invoice, order confirmation or bank statement entry.
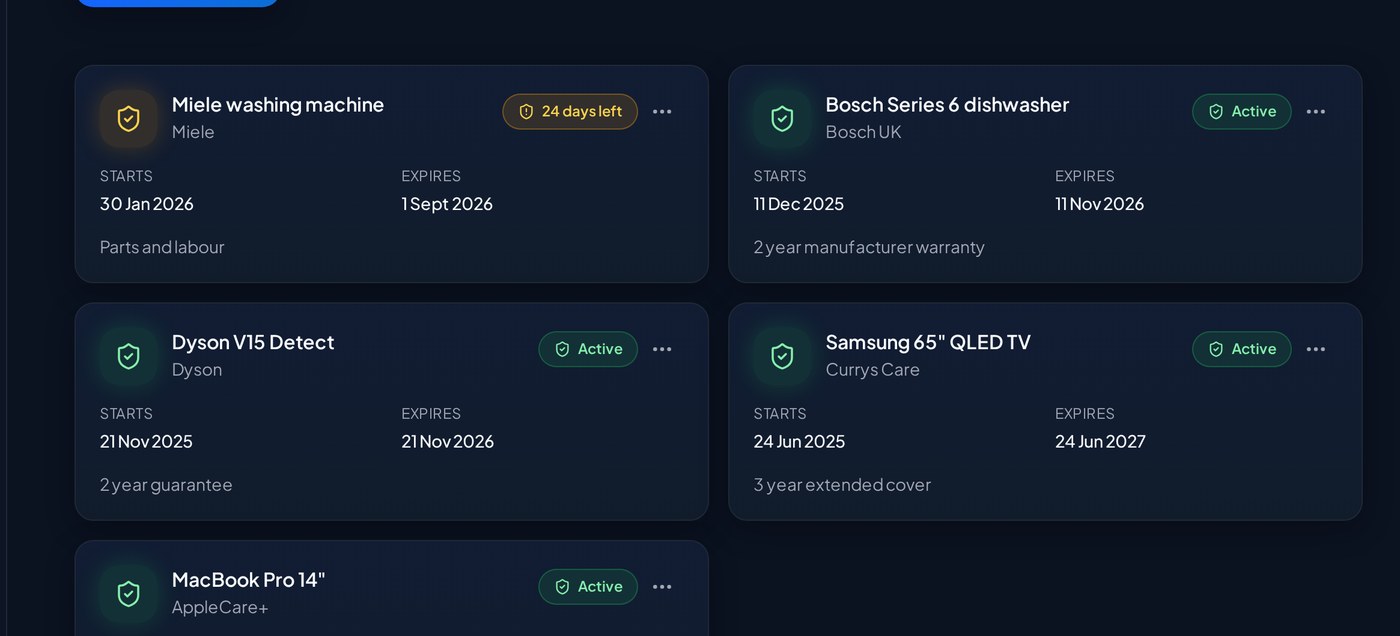
- Date of purchase — Which drives depreciation and, on some policies, the basis of settlement.
- Value — Ideally replacement cost, with something behind the figure rather than a round number.
- Valuations for specified items — Jewellery, watches, art and collections often exceed a policy's single-item limit and need to be listed separately.
Valuing contents without guessing
Most contents policies settle on a 'new for old' basis, meaning replacement cost rather than what the item is worth second-hand. That's why an honest inventory usually produces a higher total than people expect: you are pricing what it would cost to buy again today.
Keep the price you paid and the current replacement value as separate figures, each with a date. When a valuation is refreshed, the old one is still part of the record — which is what lets you explain how you arrived at a number two years later.
It's also the fastest way to notice under-insurance. Adding up a room at replacement cost frequently reveals a contents sum insured that hasn't moved since the policy was first taken out.
Preparing before you ever need it
- Photograph every room, wall by wall
Open the wardrobes and cupboards. Context shots recover the things a list forgets. - List anything above your policy's single-item limit individually
Then check whether those items need to be specified on the policy. - Attach the proof as you go
Receipt, valuation certificate or order confirmation stored with the item, not in a separate folder. - Record serial numbers
For electronics, bikes and tools they support both a claim and any police report. - Store the record off-site
The evidence has to outlive the house. Cloud storage, or an account you can sign into from anywhere. - Review it once a year
Renewal is a natural prompt. Add the year's purchases and check the sum insured still looks sane.
After a burglary
Thieves take a laptop, a camera, two bikes and jewellery. The insurer wants a schedule of stolen items with values and evidence, and the police want serial numbers.
With an inventory, that's one export covering both. Without it, the claim becomes a memory exercise carried out during the worst week of the year — and the items nobody remembers are the ones nobody gets paid for.
The Insurance Inventory pack in Vekrin
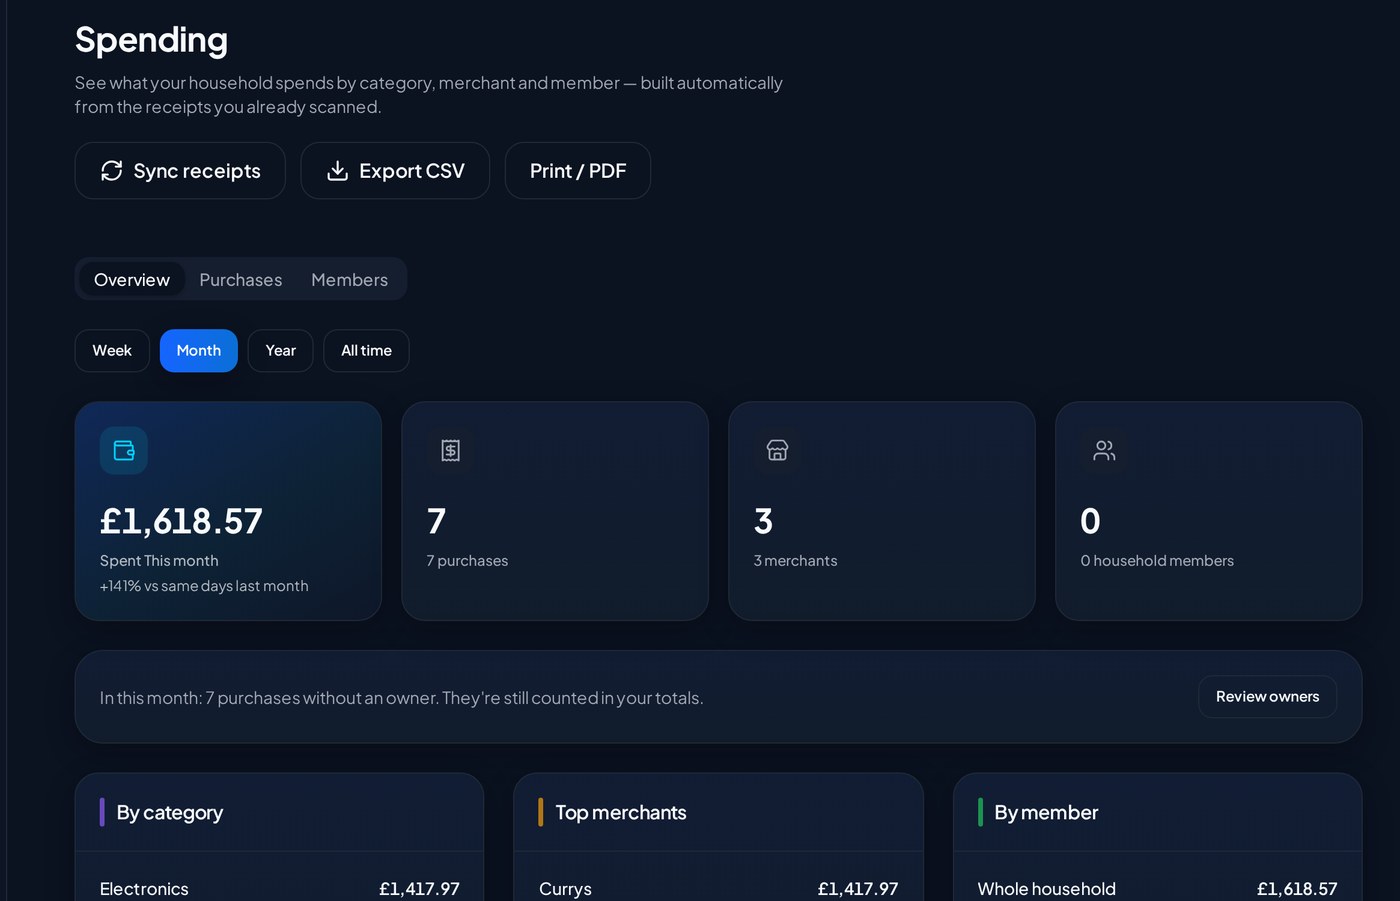
Vekrin produces an organised inventory document from the records you already keep: belongings grouped by room, with photographs, purchase details, serial numbers and dated values, plus totals your insurer can work from.
If a professional needs to see the detail, you can grant temporary read-only access to a single home rather than emailing a spreadsheet of everything you own. Access is time-limited and can be withdrawn.
- Room-by-room pack with photographs and evidence
- Price paid and replacement value recorded separately, each dated
- Time-limited, read-only access for an insurance professional
Common questions
- Do I need a home inventory for contents insurance?
- Insurers rarely require one up front, but they do require evidence at claim time. An inventory prepared in advance is the difference between claiming for what you lost and claiming for what you can still remember and prove.
- How do I value my contents for insurance?
- Most policies settle on a replacement-cost basis, so value each item at what it would cost to buy an equivalent new today, and get professional valuations for jewellery, art and other high-value items. Keep the date and the basis of each figure.
- What proof do insurers accept for stolen or damaged items?
- Typically receipts, invoices, order confirmations, bank or card statements, photographs, serial numbers, valuations and, for theft, a police crime reference. The more of these you have per item, the smoother the claim.
- How often should I update my inventory?
- Add significant purchases as they happen and review the whole record at renewal. Sum insured drifting out of date is one of the commonest causes of a shortfall.
Vekrin is not an insurer or a broker and this page is general information rather than insurance advice. Cover, evidence requirements and single-item limits vary between policies — check your own policy documents or speak to your insurer or broker.
Related reading
Be ready before the claim form arrives
Record your contents in Vekrin and keep the photographs, receipts and values in one place your insurer can work from.